
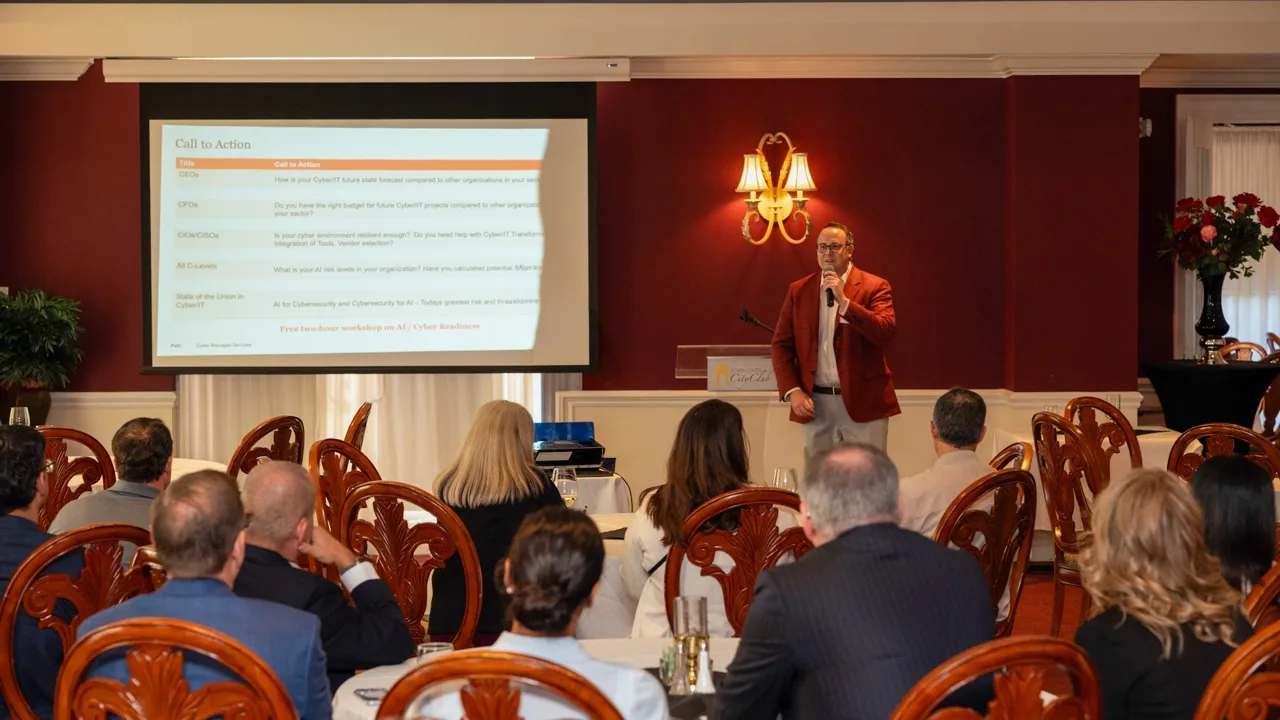
Can a business benefit from solar tax credits without installing panels on its own roof? That was one of the ideas we took away from our conversation with PwC’s Marc Morris and Brian Gallagher at the October 22 executive briefing hosted by Coastal Authority Group at Town Center City Club in Virginia Beach.
It is a useful question for Hampton Roads business owners planning for the year ahead. The opportunity involves transferable clean-energy tax credits: certain federal credits that an eligible project owner can sell to another taxpayer. Solar is one application of a broader set of eligible energy credits.
We left the event with a much better understanding of the questions to bring to our advisers. Marc and Brian gave us a great deal to think about, and solar tax credits stood out as an opportunity many owners may not know to ask about. We wanted to share that takeaway and explain what a business owner should ask next. The details below draw on current IRS guidance and PwC’s published analysis.
You can purchase a credit without owning the solar project
Under Section 6418, eligible taxpayers can transfer qualifying credits to unrelated buyers for cash. The buyer claims the credit on its tax return. The purchase payment is not also deductible. The process requires IRS registration and appropriate documentation. The IRS explains the transfer rules.
Purchasing the credit does not give the buyer ownership of the installation or its depreciation deductions. You are evaluating a tax-credit transaction, so the starting point is your business’s ability to use that particular credit. See the IRS transferability questions, including question 14.
What a purchase could look like
Here is a simplified example, assuming a business has $200,000 of federal income tax liability and can use a purchased $100,000 credit in full.
| Cash outlay | Without a purchase | With a purchase |
|---|---|---|
| Price paid for the credit | $0 | $90,000 |
| Remaining federal income tax | $200,000 | $100,000 |
| Combined outlay | $200,000 | $190,000 |
The difference is $10,000 before transaction costs. Legal fees, tax-advisory fees, insurance and other expenses would reduce that amount. The $90,000 purchase price is hypothetical, not a current quote, and this example does not model state taxes or every limitation.
Ask for a written comparison of the purchase price, all fees, payment timing and the amount your tax team expects you to use. That gives you a more meaningful number than an advertised discount.
A large tax bill does not automatically make you eligible
Individuals, trusts, estates, closely held C corporations and personal service corporations face passive-activity restrictions. The IRS says they generally can use purchased credits only against passive-income tax liability; most investment income does not qualify as passive income for this purpose. Read the IRS explanation in question 15.
For a local business owner, this is the first conversation to have with an accountant: Which taxpayer would buy the credit, and what tax liability could it actually offset? Business income and an owner’s personal tax bill should not be treated as interchangeable.
The project details matter after the sale, too
PwC’s published analysis explains that the 2025 tax law changed clean-energy timelines and added restrictions involving foreign entities and supply chains. Transferability remains available, but project and transaction eligibility need careful review. Read PwC’s overview of the changing energy-credit landscape.
For certain transferred investment credits, the buyer bears the federal tax responsibility if a recapture event requires previously claimed credits to be repaid. The IRS addresses recapture in question 13. A contract or insurance policy needs to be evaluated alongside that responsibility.
Before committing cash, bring these questions to the discussion:
- Which credit is being sold, and what supports its amount?
- Which construction and operating dates affect eligibility?
- What happens if the IRS reduces or disallows the credit?
- What protection does the contract provide, and who can fulfill it?
- If insurance is proposed, what does it exclude?
Continue the conversation with Marc Morris
For us, the value of bringing local leaders together is having a useful conversation that continues after the event. Solar tax credits were one key takeaway from Marc Morris and Brian Gallagher, and a subject worth exploring with the right advisers.
To learn more about transferable energy tax credits and questions to consider for your business, contact Marc Morris, Director at PwC.
Email Marc: marc.a.morris@pwc.com
Call Marc: 919-538-3987
Explore more CVA resources on Financial Services, Wealth Management and local business.
General education, not individualized tax advice. Sources checked November 2, 2026.


